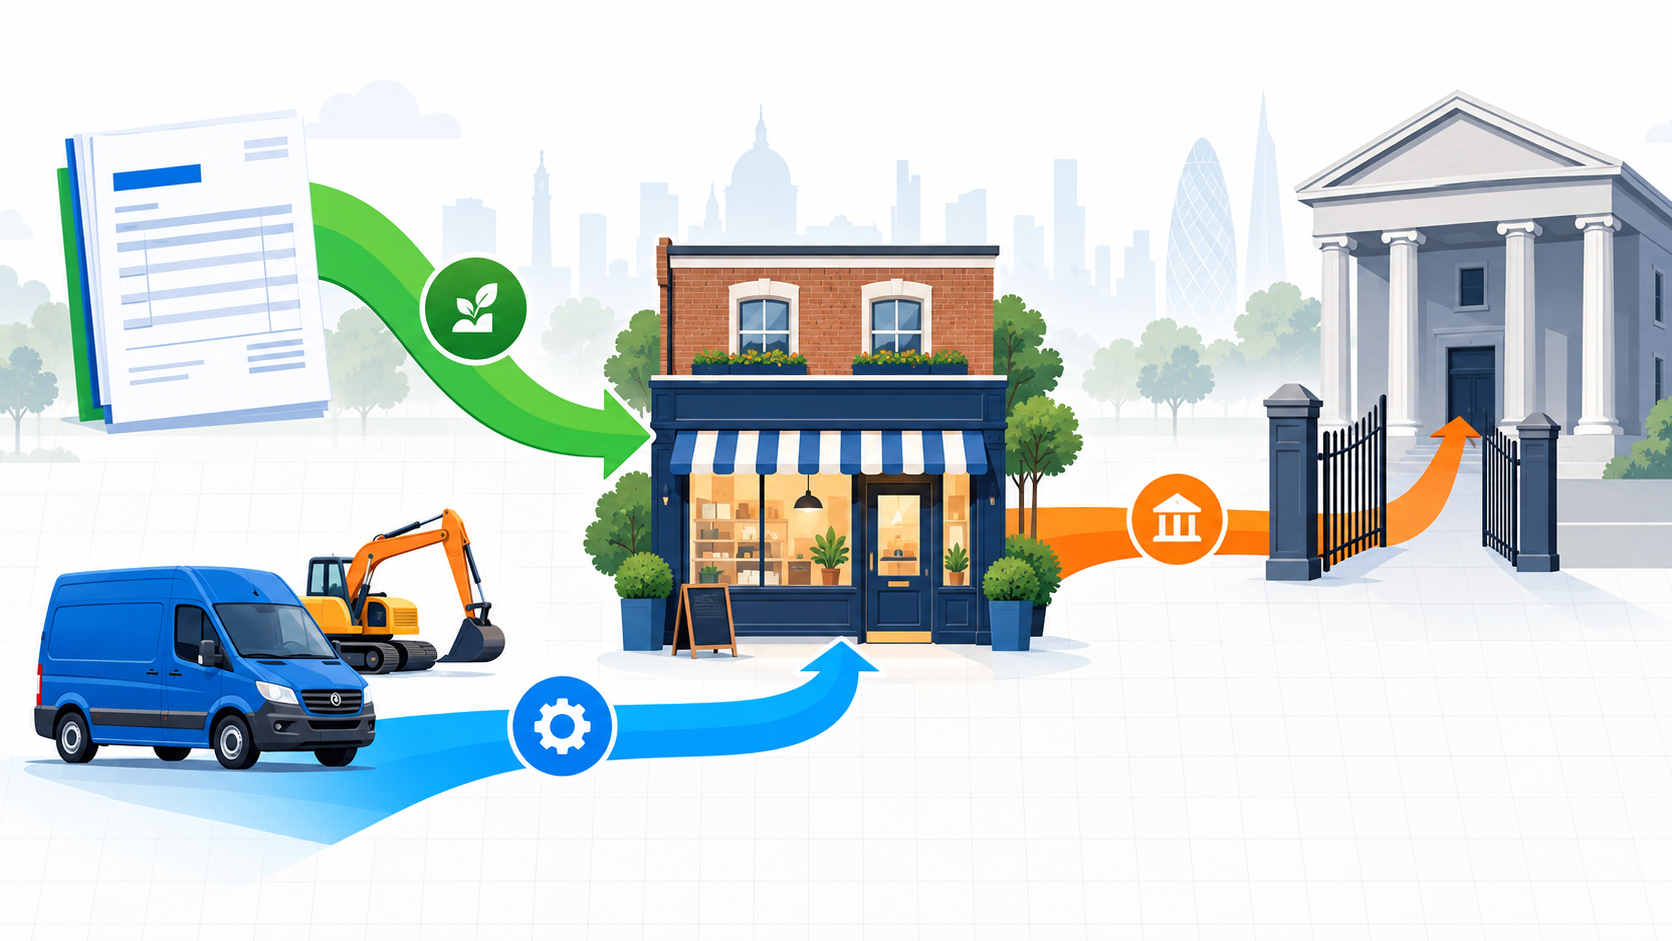
Credit is available across the UK business market, but smaller firms may still encounter a more selective lending environment. The Bank of England’s September 2026 business-conditions report says credit supply continues to exceed demand while banks prefer larger, existing customers. At the same time, invoice discounting and asset finance facilities are growing.
That combination can sound contradictory. In practice, it shows why an assessment of the overall lending market does not necessarily describe the experience of an individual SME. The type of finance, the provider, the business’s sector and trading record, and the assets supporting a facility can all affect availability and terms.
What did the Bank of England report?
The Bank of England published its latest Agents’ summary of business conditions on 11 September 2026. The report draws on intelligence gathered by the Bank’s regional Agents in the six weeks to mid-August.
Its section on corporate credit conditions identified several important features of the market:
- Credit supply continued to exceed demand, and the gap had widened modestly across businesses of all sizes.
- Banks were prepared to lend across the market but preferred larger, existing clients.
- Competition for viable borrowers had increased.
- Second-tier funders remained competitive by offering quicker decisions and accepting more risk, rather than competing mainly on price.
- Asset finance for investment and invoice discounting facilities had grown.
- Lender appetite remained lower for smaller firms and for some construction and hospitality businesses with a weak track record.
The report also said distressed borrower levels remained low and that appetite for borrowing was cautious because of the subdued economic outlook.
How can credit supply be strong while smaller firms face tighter choices?
“Credit supply” is an assessment of the market as a whole. It does not mean every business will qualify for every product or receive the same terms.
A lender may be willing to provide more finance overall while concentrating that capacity on established customers, stronger sectors or transactions supported by suitable assets. Smaller companies can have shorter trading histories, less management information, fewer assets to offer as security or greater dependence on a small number of customers. Those characteristics do not make finance unavailable, but they can affect the number and type of providers willing to consider an application.
Demand matters too. If businesses are cautious about borrowing, lenders may compete more strongly for the applicants that meet their criteria. The result can be competitive pricing for some borrowers alongside limited choice for others.
Why invoice discounting may grow in a selective lending market
Invoice finance uses eligible unpaid business-to-business invoices to support a working-capital facility. Because a provider assesses the sales ledger and the businesses that owe the invoices, the decision is not based solely on the applicant’s balance sheet or availability of property security.
The British Business Bank explains that invoice finance may be available where another lending product cannot provide the required amount. It also says the facility can grow as eligible sales increase, although the amount available will reduce if turnover or eligible invoices fall.
Invoice discounting is generally a finance-only arrangement in which the business continues to manage its sales ledger and collections. Invoice factoring normally includes credit-control support from the provider. The most appropriate structure, if any, depends on factors including turnover, customer quality, internal credit-control capability and whether the business wants customers to know that a facility is in place.
Growth in invoice discounting does not establish that it is suitable or cheaper for every business. Providers can apply concentration limits, minimum fees, recourse terms and eligibility rules. A meaningful comparison therefore needs to cover the service fee, funding charge, advance percentage and operational conditions—not only the headline rate.
What does growth in asset finance indicate?
Asset finance links funding to equipment, machinery or vehicles. This can allow a business to spread the cost of an investment rather than using a large amount of cash at the outset.
The British Business Bank’s Small Business Finance Markets 2025/26 report said new SME asset-finance business increased by 4% in 2025. It also noted that asset finance supports a substantial share of investment in vehicles, machinery and equipment.
Asset finance can be considered where the commercial need is a defined purchase. The total payable, deposit, term, ownership position, maintenance responsibilities and any final or balloon payment can be more informative than the monthly figure alone.
Where do business loans fit?
Business loans remain a broad option for one-off expenditure, investment or temporary cash-flow requirements. They can be unsecured or supported by business assets or guarantees, and repayment structures vary.
A loan may also be used as short-term funding while a longer-term facility is being assessed, although this can create overlapping costs and commitments. Comparing the term of the borrowing with the period over which the business expects to benefit from it helps reveal whether the repayment profile fits the underlying requirement.
The wider cost environment also remains relevant. The Bank of England held Bank Rate at 3.75% in September, but reported that market rates had passed through to the lending rates faced by businesses. Our recent analysis explains what the September Bank Rate decision may mean for SME finance.
What should a business-finance comparison include?
The Bank’s report suggests that provider type and facility structure can materially affect the options available to a smaller company. A factual comparison can consider:
- Purpose: whether the requirement relates to unpaid invoices, a specific asset, a one-off project or general working capital.
- Amount and duration: how much is required and whether the need is temporary, recurring or linked to growth.
- Repayment or funding profile: whether fixed repayments, a revolving limit or availability linked to invoices better matches expected cash inflows.
- Total cost: interest or discount charges, service fees, arrangement fees, valuation costs and any minimum charges.
- Security and recourse: which assets, invoices or guarantees support the facility and what happens if a customer does not pay.
- Operational requirements: reporting, credit control, covenants, audits and the time required to establish and manage the facility.
The starting point is the business requirement rather than the assumption that one product is universally preferable. Our business funding options overview explains the main differences among invoice finance, asset finance and business loans.
Which sectors may face greater selectivity?
The Bank’s Agents reported less lender appetite for some construction and hospitality firms with weak track records. This does not mean businesses in those sectors cannot obtain finance. It indicates that lenders may examine trading history, contracts, customer concentration, margins and cash-flow resilience particularly closely.
Sector conditions can also affect the most useful form of funding. A contractor waiting for certified invoices presents a different funding profile from a hospitality business with mainly immediate consumer payments, while a manufacturer buying equipment has a different need again.
Frequently asked questions
Is business credit widely available in the UK in 2026?
The Bank of England’s September Agents’ report says overall credit supply exceeds demand. It also says banks prefer larger, existing clients and that appetite is lower for some smaller firms, so individual access remains uneven.
Why are invoice discounting facilities growing?
The Bank reported growth in invoice discounting but did not identify a single cause. One relevant feature is that invoice finance is supported by eligible receivables and can provide working capital that changes with the sales ledger. That does not make it suitable for every business.
Is a second-tier funder necessarily more expensive?
Not necessarily. The Bank reported that second-tier funders compete through speed and risk appetite rather than mainly on price. Actual costs and terms vary by provider, structure and applicant, so current quotations need to be compared on a like-for-like basis.
Can invoice finance operate alongside a business loan or asset finance?
It can in some circumstances. The British Business Bank notes that invoice finance can work alongside term loans, asset-based lending and asset finance. Existing security, covenants and intercreditor requirements may affect whether facilities can be combined.
Sources
- Bank of England: Agents’ summary of business conditions, September 2026, published 11 September 2026.
- British Business Bank: Invoice finance guidance.
- British Business Bank: Small Business Finance Markets 2025/26.
This article is for general information only. It does not constitute financial, legal, tax or other professional advice. Finance availability, pricing and terms depend on the provider and the applicant’s circumstances.